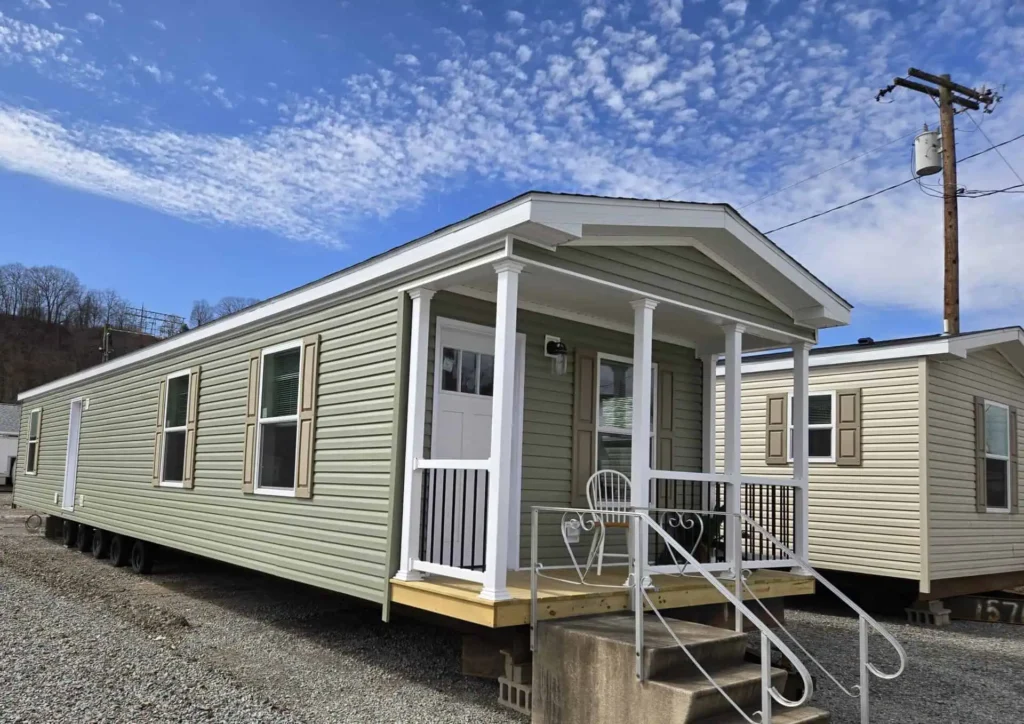
2026 Market Update: Sitting here at my desk on the lot, I’ve seen a massive shift this year. With traditional housing inventory staying exceptionally tight throughout 2026, manufactured homes are now the premier choice for first-time buyers. Lending options have expanded significantly—meaning we are locking in better rates and more flexible terms for buyers who know where to look, how to prepare, and how to navigate state-specific regulations.
When you walk onto our lot looking to purchase your first mobile home, it is an exciting prospect, and understanding the financing options available is your first critical step. As a dealer who works with buyers every day, I created The Ultimate Guide: How to Secure Mobile Home Loans for Your First Purchase “Near Me” to empower you with knowledge and debunk common industry misconceptions. Many prospective buyers feel overwhelmed, but with the right information and a trusted dealer partner, securing a loan for your dream manufactured home is a straightforward process.
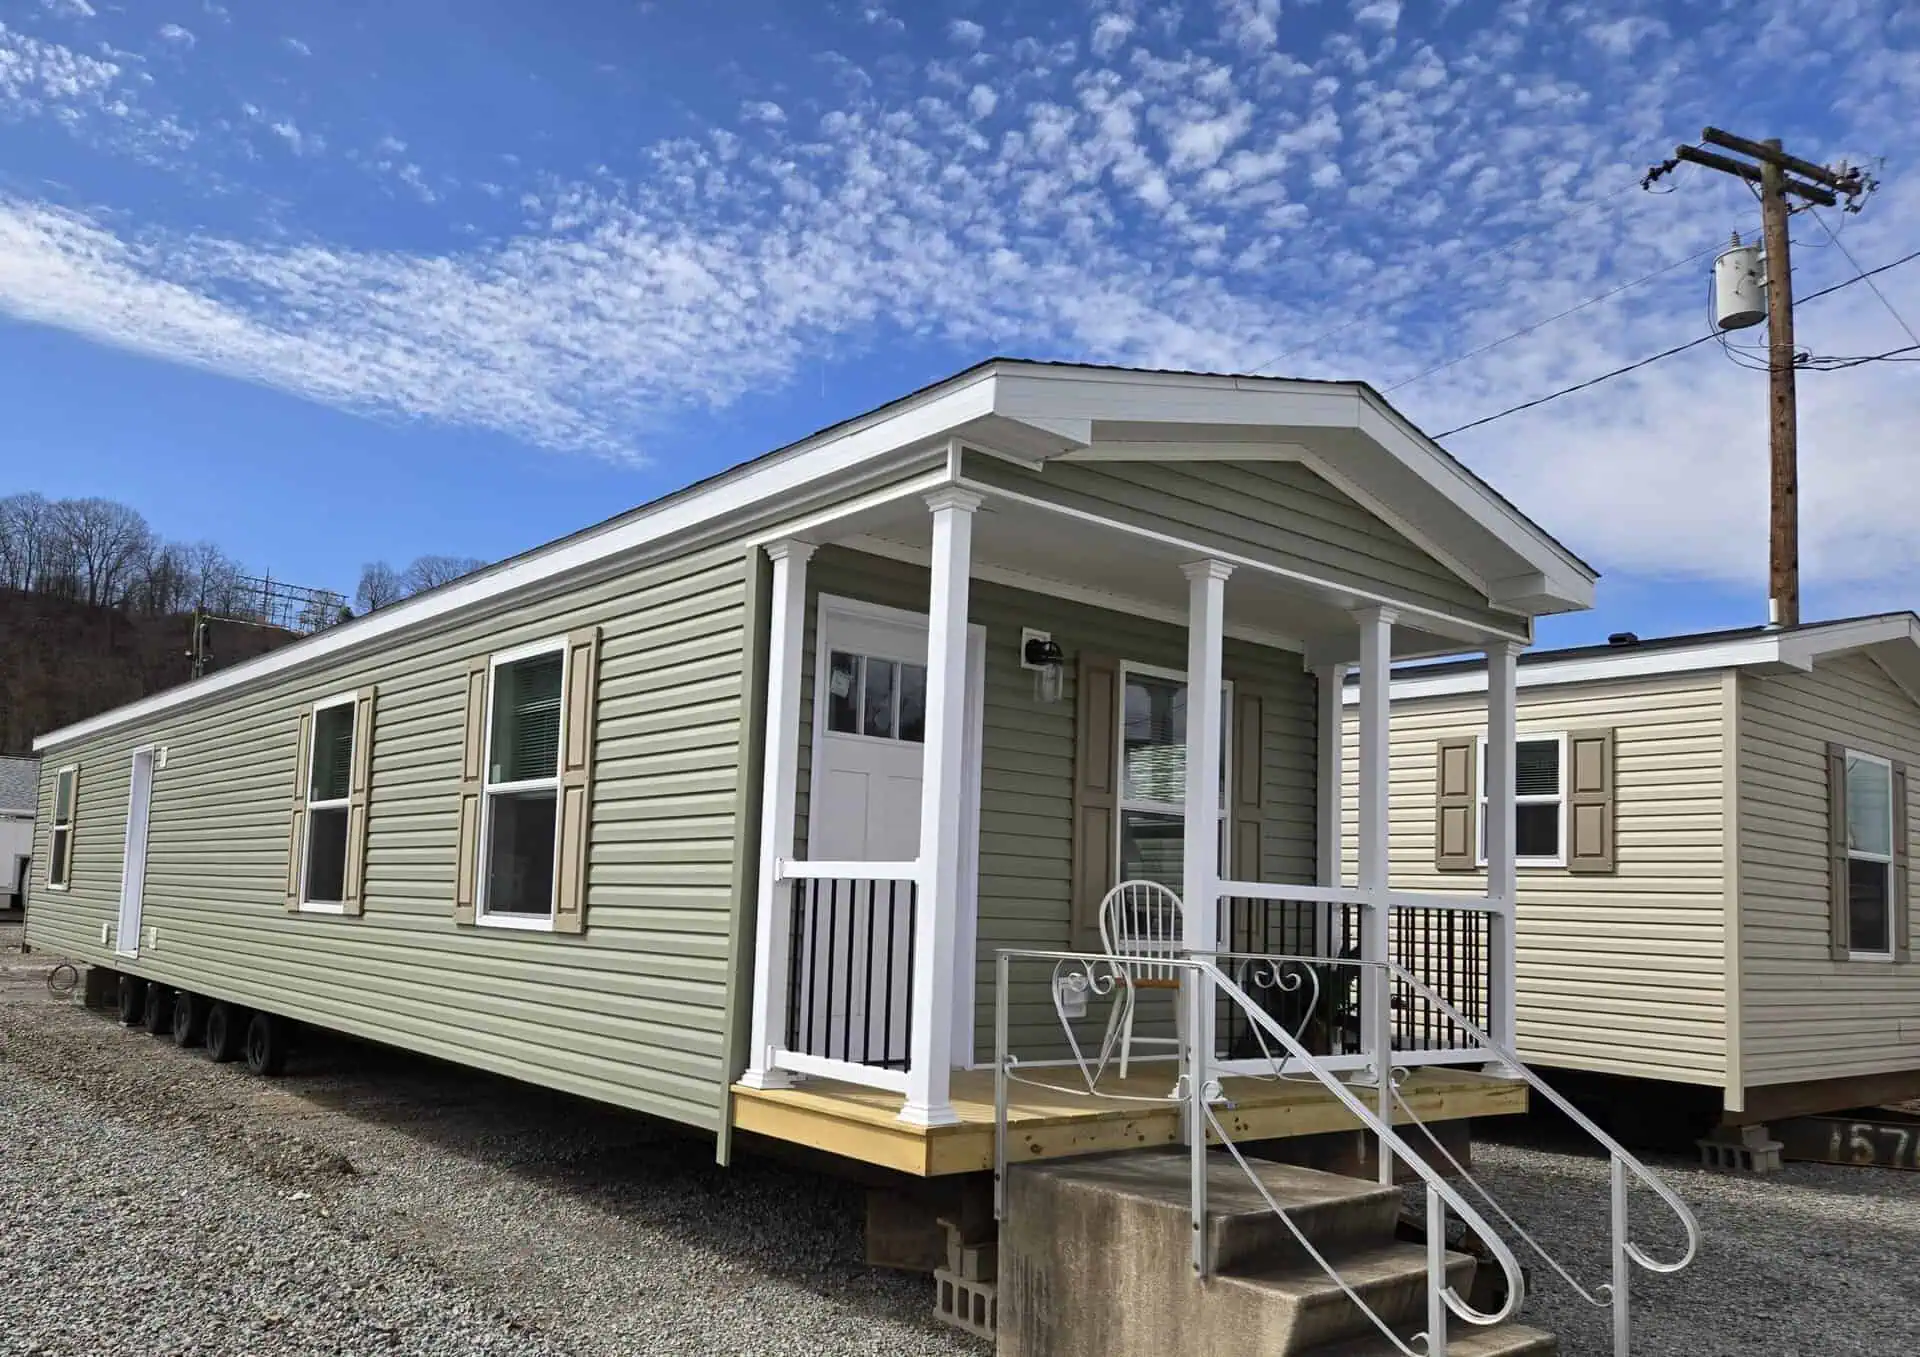
How Do First-Time Buyers Secure Mobile Home Financing?
Are Mobile Home Loans Impossible to Get for First-Time Buyers?
Short answer: No! First-time buyers have numerous avenues, including FHA, VA, and chattel loans, tailored specifically for manufactured housing.
The idea that financing is out of reach couldn’t be further from the truth. When buyers sit across from me, they are often surprised to learn about options like FHA loans (Federal Housing Administration), which are specifically designed to make homeownership more accessible with lower down payments and flexible credit requirements. VA loans offer exceptional benefits for eligible veterans, often with zero down. The key is to understand your credit profile and connect with lenders who specialize in manufactured housing. The Consumer Financial Protection Bureau (CFPB) offers excellent baseline resources on mortgage options that apply here as well. For instance, exploring relevant inventory can often provide insights into homes that qualify for various loan programs. A strong credit score is helpful, but even buyers with less-than-perfect credit find solutions when we connect them to the right specialized lenders.
Do Mobile Homes Depreciate in Value Over Time?
Short answer: Not necessarily. Modern manufactured homes, particularly those permanently affixed to owned land, often appreciate similarly to site-built properties.
This is an outdated stereotype we constantly bust on the lot. Modern manufactured homes, when placed on land you own, often appreciate right alongside traditional site-built homes. Factors influencing appreciation include location, market demand, community amenities, and the high-quality build of the home itself. Today’s manufactured homes are constructed to stringent HUD codes, ensuring incredible durability. Many of our buyers are thrilled to see long-term equity growth in their property over the years.
Do All Mobile Home Dealers Offer the Same Financing Rates?
Short answer: Absolutely not. A dealer’s specific lender network and expertise dictate the loan terms and rates you are offered.
Assuming all dealers offer the same financing is a critical mistake. I spend hours every week building relationships with specialized manufactured housing lenders. An experienced dealer acts as your advocate, presenting multiple financing solutions tailored to your individual needs. We understand the nuances of different loan products and guide you through underwriting efficiently. Seeking out a dealer known for transparent practices and strong lender ties—like our team at Comfort Mobile Homes—is paramount to locking in the most competitive rates available.
Chattel Loans vs. Conventional Mortgages: Which is Faster for Mobile Homes?
Short answer: Chattel loans finance only the home itself and are typically processed much faster than conventional mortgages, which require you to finance the home and land together as real estate.
When buyers sit down at my desk, their biggest point of confusion is usually deciding between a chattel loan and a conventional mortgage. I always emphasize that specialized dealership financing—primarily through chattel loans—is often significantly faster and more accessible than going to a traditional bank. A chattel loan is a personal property loan. Because it only covers the manufactured home itself, the underwriting process completely skips the lengthy real estate appraisals, land surveys, and title processing that bog down traditional mortgages.
If you are placing your home in a mobile home park or a leased-lot community, a chattel loan is exactly what you need. Traditional banks often shy away from manufactured housing unless the home is permanently affixed to land you own. By leveraging our dealership’s specialized lending network, we bypass the conventional banking red tape. Even government-backed programs recognize the importance of these specialized loans; for example, the HUD FHA Title I program is specifically designed to insure personal property loans for manufactured homes. This streamlined approach gets you the keys to your new home weeks—sometimes months—faster than a conventional bank mortgage.
How Do Florida’s Wind Zone and Title Requirements Impact Financing?
Short answer: In Florida, lenders strictly require HUD Wind Zone II or III certification. You must also navigate distinct FLHSMV titling rules and specific coastal insurance mandates before your loan is approved.
One critical area where we see first-time buyers stumble is local compliance—especially here in the Sunshine State. If you are financing a manufactured home in Florida, lenders will not approve your loan without verifying the home’s HUD wind zone data plate. Because of hurricane risks, Florida mandates that homes be built to at least HUD Wind Zone II or III standards, depending on your exact county.
Additionally, the title process directly impacts your loan structure. In Florida, mobile homes are initially titled through the Florida Highway Safety and Motor Vehicles (FLHSMV) department as personal property. If you own the land and want a conventional or FHA mortgage, I always advise navigating the process to “retire the title.” This legally reclassifies the home as real property. Finally, state-specific windstorm and flood insurance mandates are heavily scrutinized by lenders during underwriting, as the higher premiums directly affect your debt-to-income (DTI) ratio. Getting ahead of these Florida-specific mandates with our team will speed up your loan approval immensely.
Securing a mobile home loan for your first purchase doesn’t have to be a daunting task. By debunking common myths, understanding the strategic benefits of chattel financing, and preparing for Florida’s specific wind zone requirements, you’re well on your way to making an informed decision. Remember, personalized guidance from experts on the lot is invaluable. Your dream home is more accessible than you think.
FAQ
What credit score do I need for a mobile home loan?
While requirements vary by lender and loan type, a credit score of 580 to 620 is generally the starting point for government-backed programs like FHA. However, specialized chattel loans may have different criteria. We recommend speaking directly with us to assess your specific situation and match you with a lender that fits your exact profile.
Can I finance a manufactured home if it sits in a leased-lot park?
Yes. Because the home is situated on land you don’t own, you cannot use a standard conventional real estate mortgage. Instead, you will use a chattel loan (a personal property loan), which we set up daily for buyers moving into residential mobile home communities.
How do I verify if my land is zoned for a manufactured home?
You should visit your local county or city building department website. Look for the zoning maps or municipal codes section, or simply call their planning office directly with your parcel number to confirm that manufactured housing is a legally permitted use on your specific lot.
How do I know what HUD Wind Zone my Florida home needs?
Florida counties are divided strictly into Wind Zone II and Wind Zone III. Coastal areas like Miami-Dade and Broward require the more stringent Wind Zone III, while inland and northern counties generally require Wind Zone II. We always check the home’s HUD data plate against your specific county’s building codes before finalizing any purchase or financing application.
Ready to find the perfect mobile home and explore your financing options? Our team is here to help you every step of the way, making your homeownership dreams a reality today!
Ready to find your dream home? Browse our inventory options or reach us through our contact page.